01
The foundation
Protection with a bigger picture.
Understand permanent life insurance and how a death benefit can help protect the people and priorities that matter to you.
INDEXED UNIVERSAL LIFE. EXPLAINED.
Protect the people you love.
Discover possibilities for the life you’re living.
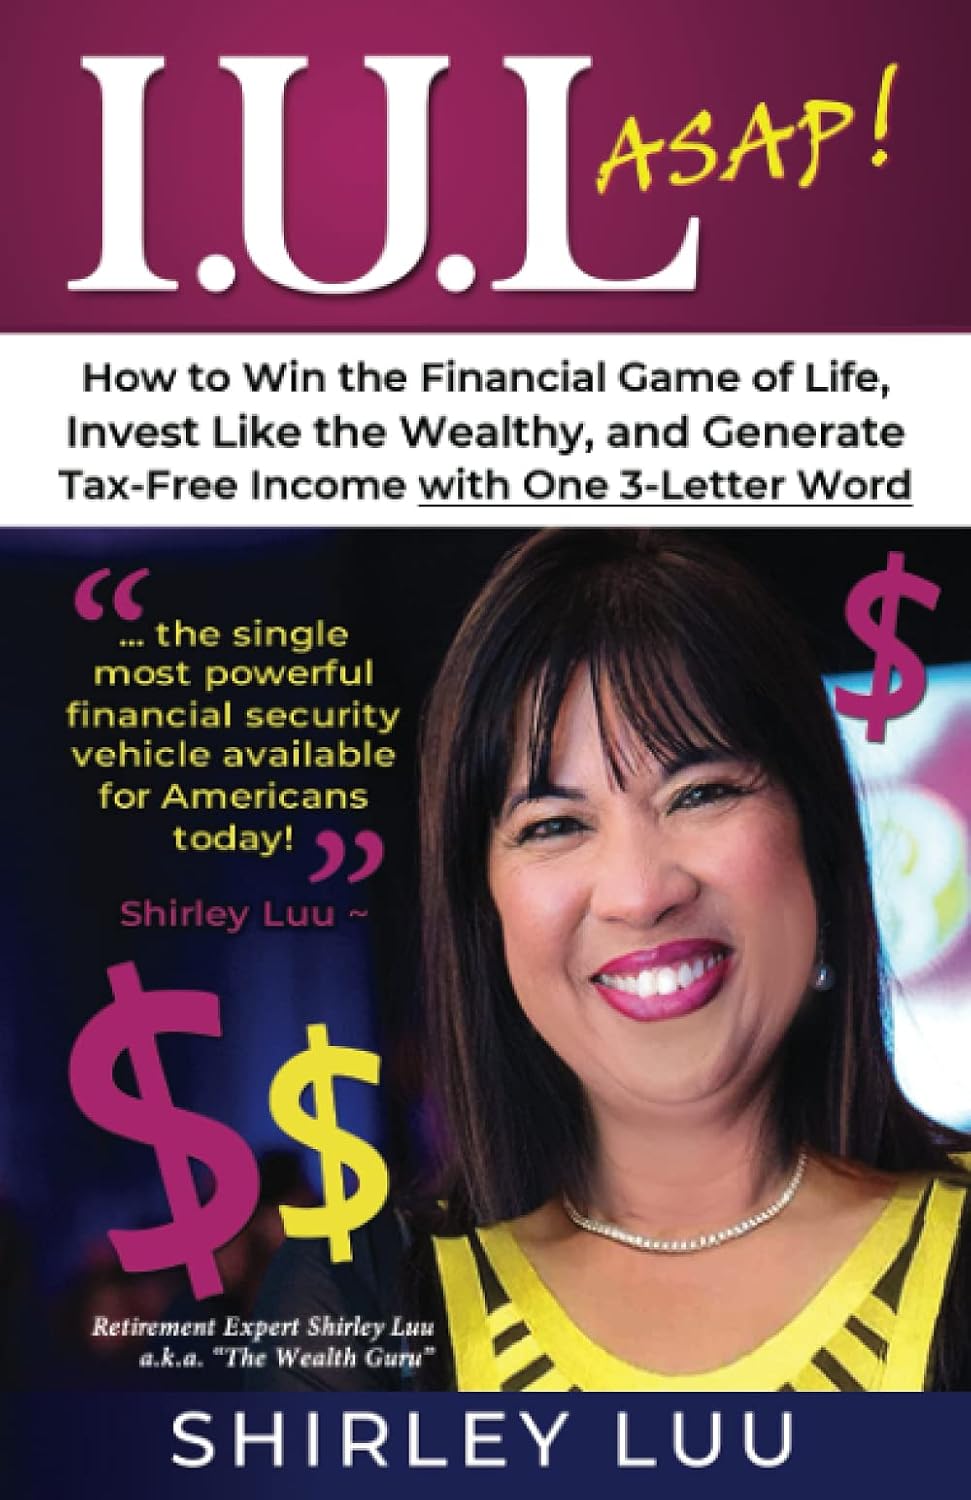
Shirley Luu’s guide to understanding cash value life insurance—and the role it could play in your financial future.
★★★★★4.6 on Amazon · 664 ratings
FINANCIAL EDUCATION. POSSIBILITIES FOR LIFE.
What if life insurance could play a part in the life you’re living, as well as the legacy you leave?
IUL ASAP brings indexed universal life insurance into focus. Shirley Luu explains the concepts in everyday language, helping you understand how protection and cash value can work within one policy.
Explore how an IUL could support different chapters of your life—and the costs, commitments and questions that deserve a closer look.
Explore the book on AmazonThe foundation
Understand permanent life insurance and how a death benefit can help protect the people and priorities that matter to you.
The potential
Explore index-linked interest, crediting floors and tax-deferred growth—along with the caps and policy charges that shape the result.
The flexibility
Learn how funding, coverage and access to cash value may adapt as your income, family and goals evolve.
The life ahead
Discover potential uses for cash value and available living-benefit riders, from future opportunities to support during a qualifying illness.
IUL stands for indexed universal life.
Start with what matters to you.
A QUESTION WORTH ASKING
The “I” in “IUL” stands for indexed. Your policy can earn interest linked to an index, without investing directly in the market. A crediting floor limits negative index credits, while caps, participation rates and policy costs help determine the actual outcome.
A 0% crediting floor does not prevent cash value from declining due to policy charges or loans.
A QUESTION WORTH ASKING
The “U” stands for universal—and flexibility is the idea behind it. Within policy limits, you may adjust premium payments, change coverage, or use available cash value for different goals. An IUL can be designed with the chapters ahead in mind.
Lower funding can cause a policy to lapse. Coverage increases may require underwriting; premium limits and tax rules apply.
A QUESTION WORTH ASKING
The “L” stands for life insurance. An IUL is designed for lasting coverage when properly funded. Available living benefits may offer access to part of the death benefit during a qualifying illness, while the remaining death benefit can help support the people you leave behind.
Riders, qualifying conditions and costs vary. Accelerated benefits generally reduce the amount paid to beneficiaries.
An IUL is a life insurance policy. Features, costs and suitability vary. The book helps you understand the questions; a personal conversation helps you explore the answers.
Rating and count verified September 17, 2026. Ratings can change.
Read the Amazon reviews
PREFER TO LISTEN?
Listen to Chapter 1 of IUL ASAP free.
Enter your email and we’ll send your private listening link immediately. Open it on your phone and choose your preferred podcast app. No payment or Audible membership is needed.
COMPLIMENTARY · NO OBLIGATION
Already finished the book? Still turning over a few questions? Talk with a licensed financial professional who is a Shirley Luu Associate about the people, priorities and plans that matter to you.
Choose an available time in the calendar.
Prefer a separate window? Open the IUL consultation calendar ↗
Loading available appointments…
If the calendar does not load, book directly on Calendly ↗.
A FEW GOOD QUESTIONS
Anyone who wants a clearer understanding of indexed universal life insurance—whether you’re protecting a growing family, exploring future income possibilities, or thinking about your legacy. You don’t need a financial background to begin.
No. An IUL is life insurance. Interest may be linked to an index, but you do not invest directly in that index. The policy’s crediting terms determine interest, and insurance costs and other charges still apply.
Depending on the policy and available value, loans or withdrawals may provide access. They can reduce cash value and the death benefit, incur interest or charges, and increase lapse risk. Tax treatment depends on policy status and how money is accessed. Review the details with a licensed professional and tax adviser.
You may have options to change the amount or timing of premiums and adjust coverage, within policy limits. You still need sufficient funding to keep the policy in force. Coverage increases may require underwriting, and premium changes can affect tax treatment.
No. You’re welcome to book a complimentary conversation whether you’ve read every page or are just getting started. Bring the questions you have today.
IUL ASAP is available in paperback, Kindle and audiobook editions through Amazon. You can also request free access to Chapter 1 and receive the listening link by email.
YOUR LIFE. YOUR POSSIBILITIES.